Policy review method

Pet Insurance Plans Review

A clause-led review of pet-insurance plans: distinguish benefit labels from eligible claims, financial limits and the records needed for payment.

Policy-first Independent Useful checks
Key checks

What matters on this page

Use these checkpoints to frame the literal question before reading the full guide.

Review date October 7, 2026 Sources checked then
Sample Bounded document and process examples No rating score
Outcome Clause-to-scenario analysis Not claim approval
Direct answer

A useful pet insurance plans review explains how a claim reaches a payment decision. It should identify the applicable policy, the event’s eligibility, excluded invoice lines and the reimbursement formula before assigning a conclusion. This review uses regulator guidance, official provider explanations and one explicitly identified California disclosure example; it is not a satisfaction survey or a complete ranking of current state-specific plans.

The sections below show how to verify the answer and what can change it.

Review the contract layer before the benefit label

An attractive label such as “diagnostics” is only the beginning. Ask whether the test relates to an eligible accident or illness, whether an exclusion applies, what the state amendments change and whether the expense is subject to a separate cap. A receipt proves a charge; it does not alone establish insurance eligibility. A medical record explains the clinical reason and timeline; it does not itself set the contract’s reimbursement percentage.

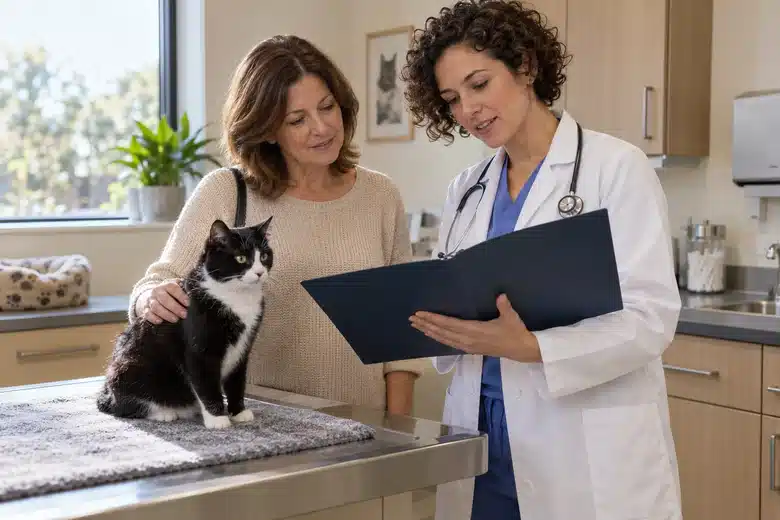
Veterinarian and owner looking at a folder beside a black-and-white cat
Illustrative record review: clinical context and contract wording play different roles in a claim decision.
Evidence matrix

Map each scenario to the controlling evidence

Scenario or question Controlling clause Condition or exclusion to inspect Evidence needed
A new diagnostic test Covered treatment and diagnostic definitions Underlying condition eligibility and waiting period Visit note, reason for test and itemized invoice
A routine annual visit Preventive/wellness benefit or exclusion Whether an add-on was purchased and its service cap Benefit schedule and service date
Follow-up medication Prescription and treatment benefits Relationship to covered condition and any limitations Prescription record and original claim history
A second unrelated problem Deductible provisions Annual versus per-condition accounting Deductible ledger and claim classification
Final reimbursement Payment calculation and limits Ineligible charges, percentage order and remaining benefit Explanation of benefits matched to invoice

A new diagnostic test

Controlling clause Covered treatment and diagnostic definitions
Condition or exclusion to inspect Underlying condition eligibility and waiting period
Evidence needed Visit note, reason for test and itemized invoice
A routine annual visit

Controlling clause Preventive/wellness benefit or exclusion
Condition or exclusion to inspect Whether an add-on was purchased and its service cap
Evidence needed Benefit schedule and service date

Follow-up medication

Controlling clause Prescription and treatment benefits
Condition or exclusion to inspect Relationship to covered condition and any limitations
Evidence needed Prescription record and original claim history

A second unrelated problem

Controlling clause Deductible provisions
Condition or exclusion to inspect Annual versus per-condition accounting
Evidence needed Deductible ledger and claim classification

Final reimbursement

Controlling clause Payment calculation and limits
Condition or exclusion to inspect Ineligible charges, percentage order and remaining benefit
Evidence needed Explanation of benefits matched to invoice

A worked claim path with an intentionally missing answer

Suppose a pet has a diagnostic visit, medication and a routine service on the same invoice. The reviewer should not assume the whole bill belongs in one bucket. First establish why the diagnostic work was ordered and whether the associated event is eligible. Next locate the medication provision. Finally decide whether the routine service has a separately purchased benefit. If the state policy is unavailable, those coverage findings remain unknown even if a product page names tests and prescriptions.

Calculation order is an evidence question

The retrieved Trupanion California disclosure, form TRU (D) 00012 CA v01.202001, includes a $1,000 eligible-invoice example with 90% coinsurance and a $250 deductible. It applies the percentage first, then subtracts the deductible, producing $650. A hypothetical deductible-first calculation would instead produce $675. The $25 difference shows why a reviewer must read the formula. This is a bounded illustration from an identified disclosure, not a statement that every current Trupanion policy uses that form or that its terms apply outside California.

A retrieved specimen reveals an extra review trap

The Pets Best Alabama specimen IAIC-PB10001-ILL, section 8H, applies 80% to $1,900 of eligible charges and then subtracts a $250 deductible, giving $1,270. Its section 2B makes specified supplemental benefits dependent on purchase, while section 2C points to the declarations for selections. Read those together: the base booklet alone cannot show which optional benefits a pet has. This Alabama example is not a claim about another state or another form.

The specimen is not the issued policy

A sample helps explain a structure. Before using it to decide your coverage, check that its state, form version, amendments and selected schedule match the offer or policy actually issued to you. An old form should never silently become evidence of a new product’s terms.

Compare with the details in front of you

Ready to check current rates?

Keep policy terms, deductible, reimbursement and limits beside the quote so the comparison stays consistent.

Find Coverage for Your Pet

Separate customer opinion from contractual benefit

A review of service might discuss how easy it was to upload documents or get an explanation. A contract review asks a different question: what did the policy promise under the relevant conditions? Fetch’s current process description asks for a paid invoice and supporting medical records; that is useful process evidence, but it is not an independent test of processing speed or approval likelihood. This review does not turn marketing time estimates or customer anecdotes into a guaranteed service standard.

Checklist

The review packet worth keeping

Identify the insured pet, policy period, state, underwriting entity and form version.
Attach the schedule and endorsements rather than reading only the base specimen.
Record the exact clause supporting each material conclusion and retain unresolved issues.
Reconcile eligible expenses, deductible, coinsurance and caps to the explanation of benefits.
Keep correspondence that clarifies a disputed or ambiguous term.

What this review can and cannot establish

The method makes a plan review reproducible and prevents a coverage label from being mistaken for an approved claim. The source sample does not include complete current state contracts for every provider, matched premium quotes or a controlled customer-service study. It therefore supports the clause questions and identified examples, not an overall best-plan score. A final purchase or claim decision requires the documents applicable to that pet and jurisdiction.

FAQ

Common questions

Does a sample policy guarantee the coverage I will receive?

No. Match it to the issued or offered state form, schedule and endorsements.

Why can a covered condition still leave part of the bill unpaid?

The policy may exclude particular charges or apply deductible, coinsurance and benefit limits. Read the payment calculation as well as the condition decision.

Is an online review evidence that my claim will be paid?

No. Another claim may involve different documents and circumstances. Use reviews to identify service questions, not to replace the contract.

Sources & editorial standards

Independent references

These links provide independent government, academic or reference background. Actual policy wording controls insurance eligibility, benefits and claims.

Pet Insurance Lens

Ready to compare with clearer inputs?

Keep the policy terms beside the price, then continue to rates when the comparison is clear.

See Insurance Rates